Skoda and Volkswagen October 2026 Sales: Slavia and Virtus Lift Monthly Totals
Electric Vehicles Pearl Daniels 851 reads
Skoda and Volkswagen sales rose 28.82% month on month, led by sharp gains for the Slavia and Virtus, while both brands remained below October 2025.
Skoda and Volkswagen’s October recovery came chiefly from two sedans. The Slavia and Virtus together added 2,645 units from September, more than the two brands’ combined net increase of 2,398. That concentration matters: several of the group’s SUVs, including the Kylaq, Kushaq and Taigun, slipped month on month. A stronger monthly total, then, doesn’t by itself show that demand has returned across the lineup.

The brands sold 10,718 cars in October 2026, up 28.82% from 8,320 in September. The improvement didn’t erase the year-on-year gap: combined sales were 12.86% below the 12,300 units recorded in October 2025. Skoda contributed 7,805 cars and Volkswagen 2,913, with both brands posting monthly gains and annual declines. The split between those comparisons matters: October brought a clear sequential rebound, while the year-earlier figures show the recovery is still incomplete.
Skoda: Slavia’s surge reshapes the mix
Skoda’s October total rose 27.91% from 6,102 in September, but remained 5.42% below its 8,252 units a year earlier. The Kylaq was still the brand’s best seller, with 3,949 cars, just over half of Skoda’s volume. Yet it was down 4.29% from September and 22.23% from October 2025. Its annual loss of 1,129 units was the largest among Skoda models. That makes the Kylaq’s scale a double-edged feature: it anchors the brand’s current volume, while also carrying much of the year-on-year weakness.
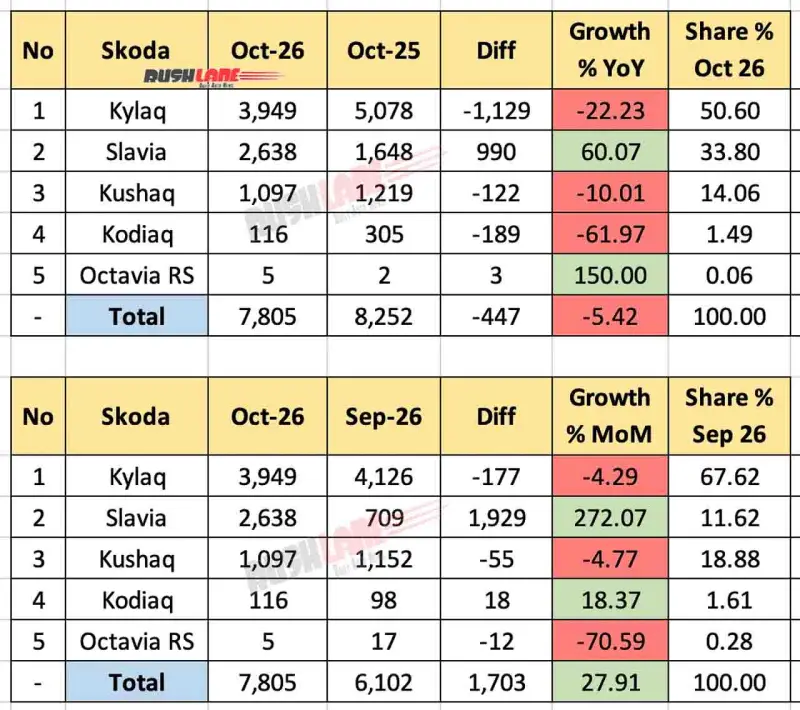
The Slavia supplied the month’s standout jump. Its 2,638 units were 60.07% above October 2025’s 1,648, and more than three times September’s 709. The month-on-month increase was 1,929 cars, lifting the sedan’s share of Skoda sales from 11.62% to 33.80%. Together, the Slavia and Kylaq accounted for just over 84% of the brand’s October deliveries. A single month can’t establish a lasting shift in demand, but the change in the sales mix is too large to dismiss as background noise.
That mix shows why Skoda’s monthly gain doesn’t signal a broad lift across the lineup. The Slavia’s jump alone was larger than the brand’s net increase of 1,703 units, while the Kylaq and Kushaq both declined from September. The Kushaq recorded 1,097 sales, down 4.77% month on month and 10.01% year on year. The figures point to a strong sedan month alongside softer volume for two of Skoda’s SUVs. Here's the thing: when one model accounts for more than the group’s net gain, the headline growth says less about the health of the full range.
Kodiaq sales moved in the other direction month to month, rising 18.37% from 98 to 116. Its October tally was still 61.97% below the 305 recorded a year earlier. Skoda also sold five Octavia RS cars, compared with 17 in September and two in October 2025. Those smaller-volume models had little effect on the brand’s overall result. The contrast is useful, though: percentage swings can look dramatic on a small base while making little difference to total deliveries.
Volkswagen: Virtus leads, Taigun remains under pressure
Volkswagen sold 2,913 cars in October, up 31.33% from September’s 2,218. Against October 2025, however, the total was down 28.04% from 4,048. The Virtus led the monthly rebound, while the Taigun posted the lineup’s largest annual decline in unit terms. This is more significant than it looks: both brands had a stronger month, but Volkswagen’s larger annual shortfall means the recovery has more ground to cover.
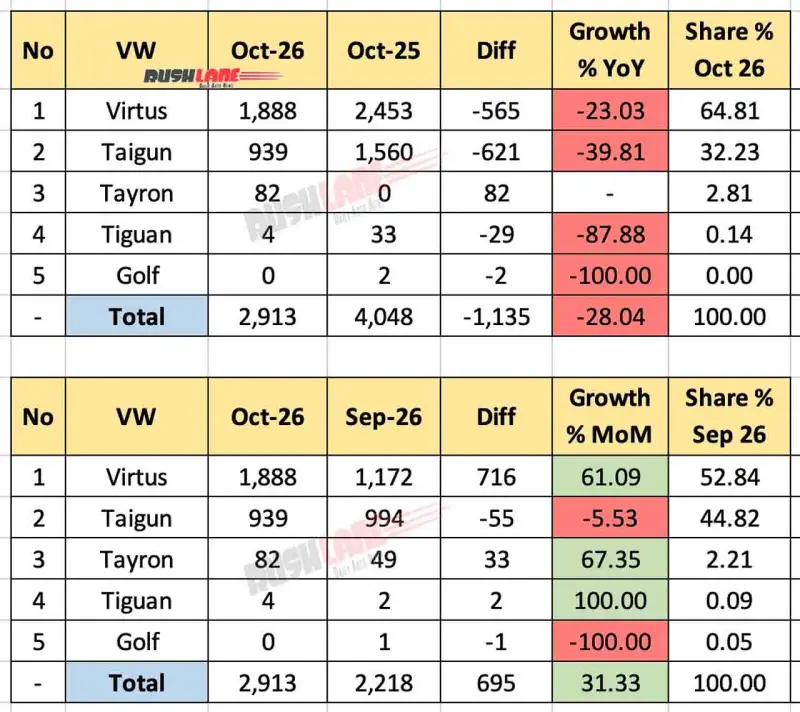
The Virtus sold 1,888 units, or 64.81% of Volkswagen’s October total. That was 61.09% more than September’s 1,172, an increase of 716 cars—slightly greater than Volkswagen’s net gain of 695. The sedan’s year-on-year comparison was weaker: October 2025 sales were 2,453, making this year’s tally 23.03% lower. Volkswagen is preparing an updated Virtus for launch in the coming weeks after the car was unveiled online. The sales figures provide a baseline for tracking whether the updated model changes the sedan’s trajectory. The launch may give the nameplate fresh attention, but these figures don’t yet show whether that will translate into sustained volume.
The Taigun placed second in Volkswagen’s lineup with 939 units, equal to 32.23% of brand sales. It slipped 5.53% from September’s 994 and 39.81% from October 2025’s 1,560. The annual shortfall was 621 units, the largest for any Volkswagen model, followed by the Virtus at 565. So while the Virtus carried the monthly improvement, both core nameplates remained below their year-earlier levels. That's the weak point in the rebound: the volume is concentrated in one model, and the other mainstay is still losing ground on both comparisons.
Among the smaller tallies, Tayron sales climbed 67.35% month on month, from 49 to 82. Volkswagen recorded four Tiguan units, compared with two in September and 33 a year earlier. Golf registered no sales, against one in September and two in October 2025. The Tiguan R-Line has been discontinued. These models are too small in the October mix to explain the broader movement, though their figures show how uneven the lineup is beyond its two volume sellers.
What the October mix says about the next stretch
Volkswagen’s next major India launch is described as a sub-four-metre SUV based on the Kylaq. The connection between the planned model and an existing Skoda SUV could give the group another route into a segment where its current sales are uneven, though the October data can’t tell us how a future launch will perform. And yet, a new nameplate alone won’t answer the immediate question: whether the existing SUVs can regain momentum.
For now, the October split leaves a clear measure to watch: whether the sedan-led monthly rebound broadens across the SUV range, and whether the updated Virtus can help reverse its year-on-year decline. If you're working in this space, the distinction between month-on-month growth and year-on-year recovery is the one to keep in view. The brands have a better monthly result, but the annual comparisons still expose the distance left to recover. One strong month. More evidence needed.